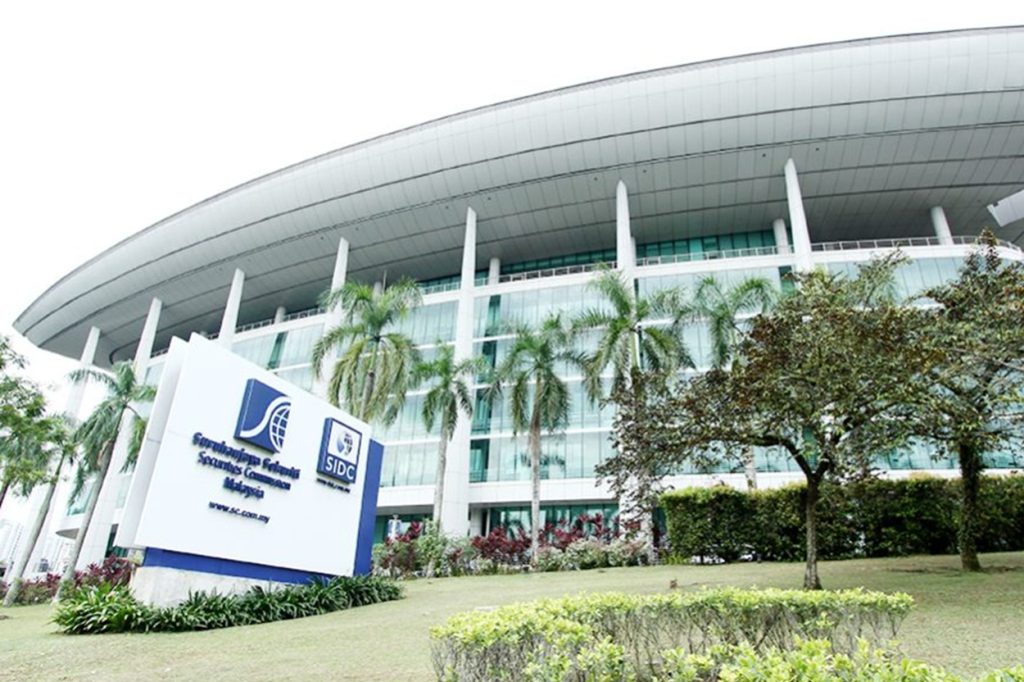
LETTER TO EDITOR, Oct 4 – At the CGI Global Governance Summit earlier in September 2026, Securities Commission of Malaysia (SC) Executive Chairman Datuk Mohammad Faiz Azmi outlined plans for an SC-led multi-stakeholder taskforce to establish a new regulatory and competency framework for company secretaries, alongside joint efforts with Bursa Malaysia to enforce fit-and-proper standards. Driven by public consultations for the upcoming Malaysian Code on Corporate Governance (MCCG 2026), the SC’s stated intent is difficult to fault on the surface. Demanding higher accountability and strategic competency from boardroom officers in public listed entities aligns with elevating governance.
Behind the rhetoric, however, lies a clear jurisdictional anomaly. Company secretaries are statutorily created, licensed, and regulated under the Companies Act 2016, a domain anchored strictly within the authority of the Companies Commission of Malaysia (SSM). While the SC has a legitimate interest in board decision-making within public listed companies, directly setting up regulatory frameworks for a profession governed by company law illustrates a broader trend: the SC’s growing practice of extending its statutory authority well beyond public capital markets.
This institutional drift extends directly into the administration of corporate trusteeship under the Trust Companies Act 1949. Trust companies in Malaysia are incorporated, registered, and overseen by the Registrar of Companies under SSM, which serves as the primary statutory custodian of Act 100. Yet, the SC has progressively asserted a parallel regulatory oversight over trust companies through licensing requirements, trustee registration regimes, and specialized guidelines under the Capital Markets and Services Act 2007 (CMSA). By imposing its own supervisory layers on trust entities—whether acting as bond trustees, collective investment scheme custodians, or digital asset custodians—the SC effectively treats SSM-registered trust companies as sub-regulated entities of the capital market watchdog. Rather than respecting SSM’s primary statutory mandate over trust companies and working through joint legislative updates, the SC continues to build overlapping regulatory hurdles that inflate compliance costs and create jurisdictional friction.
The SC’s intervention in company law is even more disruptive when applied to private corporate finance. Under Sections 72 and 90 of the Companies Act 2016, a private limited company (Sendirian Berhad) possesses the explicit statutory right to issue Redeemable Preference Shares (RPS) and Redeemable Convertible Preference Shares (RCPS) as part of its internal balance sheet structure. Furthermore, Section 44 explicitly allows private companies to raise funds via private concerns targeting specific, sophisticated investors without issuing a public prospectus. Despite this, the SC routinely intervenes in private corporate deals, reclassifying private preference shares with fixed yields or redemption terms as unapproved debentures or illegal Collective Investment Schemes under the CMSA. Applying nuclear-option public market enforcement—such as issuing Investor Alert List warnings and threatening statutory penalties of up to RM10 million and ten years’ imprisonment—to private corporate contracts between consenting commercial partners represents a profound misallocation of regulatory power.
The irony of this expansion into SSM’s domain is that it distracts the SC from where its statutory mandate is urgently required. The true testing ground for the SC’s enforcement resources lies in overseeing massive, complex public market actors like Zetrix AI Berhad—formerly MY E.G. Services Berhad—and similar public listed entities. Operating at the intersection of public concessions, cross-border Layer-1 blockchain infrastructure, digital token issuances, real-world asset tokenization, and stablecoin initiatives, companies of this scale represent the precise arena where capital market regulation is vital. Public listed entities command multi-billion-ringgit market capitalization, drive massive retail trading volume, and navigate high-stakes disclosure requirements under Bursa Malaysia Listing Requirements. Ensuring that public market announcements are accurate, preventing market manipulation, and scrutinizing complex digital asset mechanisms require aggressive, uncompromising vigil from the SC. This is where public capital risk resides, and this is where statutory resources belong.
Securities Commission Overshadowing SSM?
This dynamic exposes a double failure: expanding overreach by the SC and passive surrender by SSM. As the sole statutory custodian of the Companies Act 2016 and the Trust Companies Act 1949, SSM has remained silent while another authority reclassifies corporate share instruments, imposes parallel rules on trust companies, and dictates competency rules for company secretaries. SME directors, corporate trustees, and professional secretaries who comply fully with SSM statutory filings are left exposed to legal double jeopardy when the SC unilaterally redefines private corporate actions as capital market offenses. SSM must reclaim its legislative domain by issuing clear Practice Directions that protect private placements, defend the legal validity of instruments created under company law, and assert its sole governance over registered trust entities.
Malaysia’s corporate and financial ecosystem requires a Securities Commission that is focused, formidable, and bounded by its statutory purpose. The SC must step back from policing private corporate balance sheets, stop building parallel frameworks for SSM-governed trust companies and company secretaries, and leave private company administration to SSM. By re-anchoring its authority firmly where it belongs—enforcing rigorous transparency on public listed conglomerates, scrutinizing major digital asset offerings like Zetrix, and protecting public secondary market investors—the SC can fulfill its core statutory mandate without suffocating private enterprise or eroding institutional boundaries.
By Muhamad Firdaus bin Jumaludin
Advocate & Solicitor | Syarie Counsel
Muhamad Firdaus is an Advocate & Solicitor and Syarie Counsel with more than a decade of experience in litigation and corporate and commercial law. He is trusted by clients to advise on business and investment structuring, corporate governance, commercial contracts, joint ventures and shareholders’ arrangements, as well as risk management and commercial dispute resolution. His practice also covers Native Customary Rights (NCR) and Sarawak Bumiputera land, Syariah law, estate and probate matters, intellectual property and franchising. By combining legal, commercial and business strategy perspectives, he delivers advice that is practical, forward-looking and aligned with his clients’ objectives.
More Stories
Malaysia Explores Opportunities to Join Embraer Aerospace Supply Chain
EPF Calls For Pension System Reforms To Secure Lifelong Retirement Income
KOSA, MegazoneCloud Highlight Korean AI and Software Firms’ ASEAN Expansion